Context, supporting details, statistics, or background information.
Contact agent: @profile instagram
The financial perspective on journalism encompasses two main areas: the focus of financial reporting as a beat and the challenges to the industry's traditional business model.
Purpose: It is used to provide clarity and precision when discussing small changes in interest rates, bond yields, or investment fund expenses, as a change of even a few basis points can be significant.Measurement: One basis point equals one-hundredth of one percentage point (0.01%).Example: An interest rate increase from 4.00% to 4.25% is an increase of 25 basis points (bps).
🖼
Finish a turn at the sector #22.
Economic labor utilities.
In clearance
24h/5 per inspection
Press release
Financial Markets
Corporate News
Personal Finance
Watchdog Role
Paywalls and Subscriptions
Digital creation Revenue Streams
Multi-channel memory architecture
Salaries
On a personal level, many journalists have to manage their financial expectations;
few make a salary exceeding $100,000 annually, with average salaries often around $50,000.
The Turnkey Domain Flipping, Resale, & Venture Capital Framework
Act I: The Expedia Travel-Focused Blueprint
This travel-focused blueprint applies the BPWC strategy to Expedia bookings, transforming vacation sales into an integrated wealth engine.
Cash In (Panels 1 & 2):Your strategy initializes with an illustrative $400 entry unit, which funds wholesale Expedia API access ($360), platform licensing ($16), and a corporate deployment margin ($24) to establish your tech baseline.
Cash Flow (Panels 1 & 3):Growth is powered by two channels: a 10% entry margin and a dominant 90% recurring Expedia booking commission. Every time clients book hotel stays, flights, or tour packages, a 4% commission on gross booking value is systematically funneled back to compound your asset pool.
Cash Out (Panel 4):As recurring client travel pushes portfolio values upward through years 4 to 6+, you secure your profits by executing a sell order, clearing the standard T+2 days funds settlement cycle, and withdrawing your cash to achieve your goals.
Act II: The Compound Investment Lifecycle
This detailed blueprint breaks down the exact revenue streams and numbers that drive your compound investment lifecycle.
Cash In (Panels 1 & 2):Your initial funding starts with an illustrative $1,850 unit deployment, which gets split directly between hardware costs ($1,200), software licensing ($300), and corporate margins ($350) to build the infrastructure base.
Cash Flow (Panels 1 & 3):The model thrives on two cash channels: a 15% deployment margin and a heavy 85% recurring web commission. Every time clients order web services or SaaS renewals, a 4% commission is collected and funneled back to compound your overall portfolio value.
Cash Out (Panel 4):After watching your value scale through years 4 to 6+, you initiate a liquid cash-out by selling your ETF shares, waiting out the standard T+2 days processing cycle, and withdrawing your money to achieve your personal goals.
Act III: The Web Commission Matrix
This timeline outlines the specialized BPWC strategy, mapping web commission channels into a structured, growing investment pool.
Cash In (Steps 1 & 2):Multiple buyers combine their money into a collective funding pool to deploy built-in server infrastructure packages, creating initial funding loops for the corporate headquarters over years 1 to 3.
Cash Flow (Step 3):High-volume client activity on the e-commerce web portal triggers a predictable 4% commission stream, channeling steady cash flow into the portfolio to accelerate compound ETF growth over years 4 to 7+.
Cash Out (Step 4):When you reach your financial milestones, you submit an ETF sell order, clear the standard T+2 business days settlement wait time, and cleanly withdraw your liquid money to fund a new home or vehicle purchase.
Act IV: Rules and Risk Contingencies
This expanded framework introduces clear starting rules and unique risks to consider when executing your personal or corporate cash cycle.
Cash In:Personal accounts kick off their growth plan with an initial deposit of $10,000 CAD, while large-scale corporate structures inject a baseline of $1,000,000 CAD followed by heavy recurring monthly deposits.
Cash Flow:Personal investors navigate severe stock market volatility to maximize growth over 7+ years. Meanwhile, corporate managers protect their operating capital over a shorter 1–6 year horizon by shielding the cash flow from interest rate spikes and credit defaults.
Cash Out:Personal accounts eventually exit the market to unlock lifetime dreams, while corporate accounts trigger an intentional cash-out to fuel sudden business expansion or safely clear outstanding corporate debt.
Act V: Personal vs. Corporate Lifecycle
This strategic matrix contrasts a high-growth personal cash lifecycle against a stable, income-focused corporate framework.
Cash In:Personal investors deposit cash into equity funds like NUSA, NINT, and NDIV for rapid growth, while corporate accounts inject cash into stable fixed-income assets like NCPB, NTGA, and NSCE.
Cash Flow:Personal portfolios accept higher risk to maximize long-term compound growth over 7+ years. Conversely, corporate portfolios focus on a shorter 1–6 year timeline to reliably manage operating cash flow and suppress market volatility.
Cash Out:Personal investors eventually cash out to fund major dreams like a new home or retirement. Corporate accounts execute their cash-out strategically to buy office equipment, fund business expansion, or repay corporate debt.
Act VI: The End-to-End Investment Journey
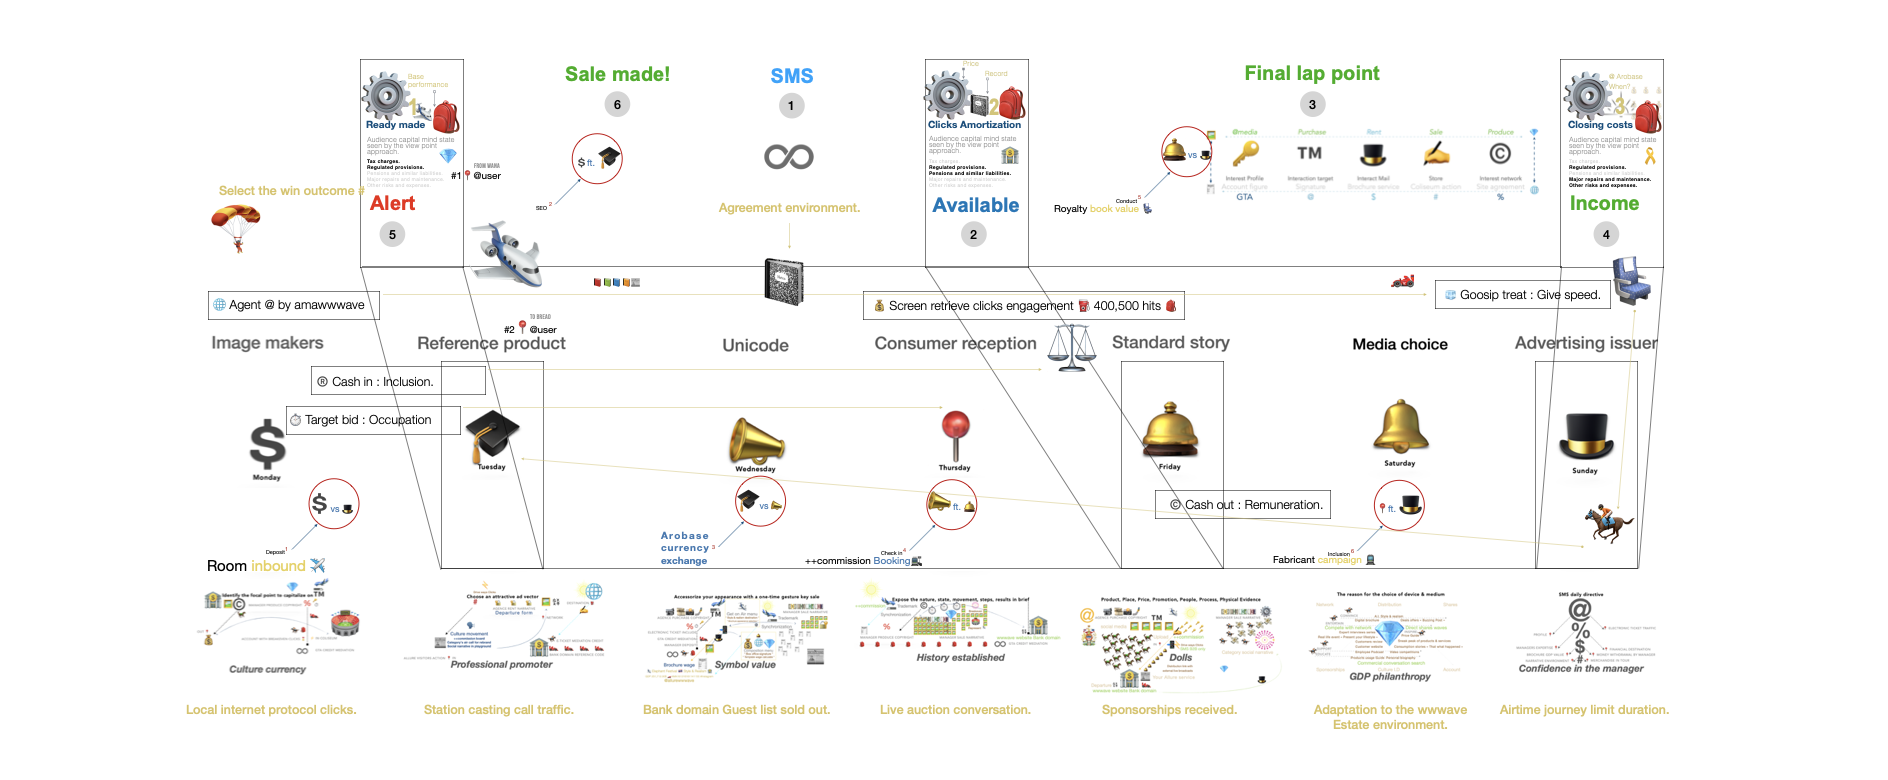
This visual timeline outlines an end-to-end investment journey by mapping out your active cash lifecycle from day one to your final purchase.
Cash In (Steps 1 & 2):You log in, open an account, and make an initial deposit to purchase an equity portfolio mix (such as NUSA, NINT, or NDIV).
Cash Flow (Step 3):Your investments grow over years 1 to 9+ through compounding and professional management, while you actively track your milestones on a dashboard.
Cash Out (Steps 4, 5, & 6):Once you hit your goal milestone, you execute a sell order, settle the funds into cold cash, and withdraw the money to make your major personal purchase—like a new car or a home.
Core portfolio building starts with a clear, three-step cycle of managing your money.
Cash In: You "Cash In" by depositing your regular savings into broad stock and bond ETFs like NUBF or NSDU.
Cash Flow: Your money then builds "Cash Flow" as the funds gather continuous dividends and interest behind the scenes. This step safely leverages broad market growth to multiply your balance without needing advanced trading skills.
Cash Out: Ultimately, you "Cash Out" by selling your expanded investments years later to enjoy your long-term profits.
Yield Strategy Comparison
NUBF provides a consistent monthly cash flow of $0.08 CAD per unit, whereas NSDU focuses on long-term capital growth with a low annual dividend yield of 0.23%.
Fund Definitions
NUBF (NBI Unconstrained Fixed Income ETF) and NSDU (NBI SmartData U.S. Equity Fund - ETF Series) are specialized exchange-traded funds managed by National Bank Investments. NUBF is an actively managed global bond fund sub-advised by J.P. Morgan Asset Management that dynamically buys global debt securities to maximize regular income while preserving your capital. Meanwhile, NSDU is a quantitatively driven stock fund portfolio-managed by Goldman Sachs Asset Management that uses data models to select high-performing American companies. Together, they allow everyday investors to balance immediate, reliable cash flow with the long-term price appreciation of the U.S. stock market.
Specific Dividend Payouts (Cash Flow)
NBI Unconstrained Fixed Income ETF (NUBF):
Distribution Amount: $0.0800 CAD per unit
Frequency: Monthly (paid on a regular basis)
Dividend Yield: Approximately 4.51% to 4.63% annualized
NBI SmartData U.S. Equity Fund (NSDU):
Distribution Amount: Approximately $0.03 CAD per unit
Frequency: Annually (paid once a year)
Dividend Yield: A minimal 0.23% (this fund automatically reinvests its profits into the underlying U.S. companies to focus on growing your core investment rather than distributing cash)
Growth Allocation Blueprint
To see how your money grows over time, you can follow this 4-step monthly deposit plan:
Establish a baseline: Start with an initial deposit (such as $1,000) to open your ETF account.
Automate your cash-in: Set up a recurring transfer of $500 every month right after payday.
Reinvest for compound growth: Let your monthly dividends buy more shares automatically.
Track long-term wealth: Watch your steady inputs compound into a significant nest egg over 10 to 20 years.
Automation & Exit Controls
Automating your cash-in builds your principal balance to maximize your final cash-out value.
Contribution: Each $500 deposit buys more ETF shares to accelerate compound growth.
Duration: You choose how many months to run the automation.
Optimal Timeline: Sticking to it for 120 to 240 months yields the best results.
Requirement: Keeping the ETF long-term is recommended but never required.
Exit Strategy: You can pause deposits or completely cash out anytime by selling your shares.
Income contract
Financial estate
Standard program run
Selected accounts
Brochure drive
Aesthetic key Concept
Major types @
Tax #
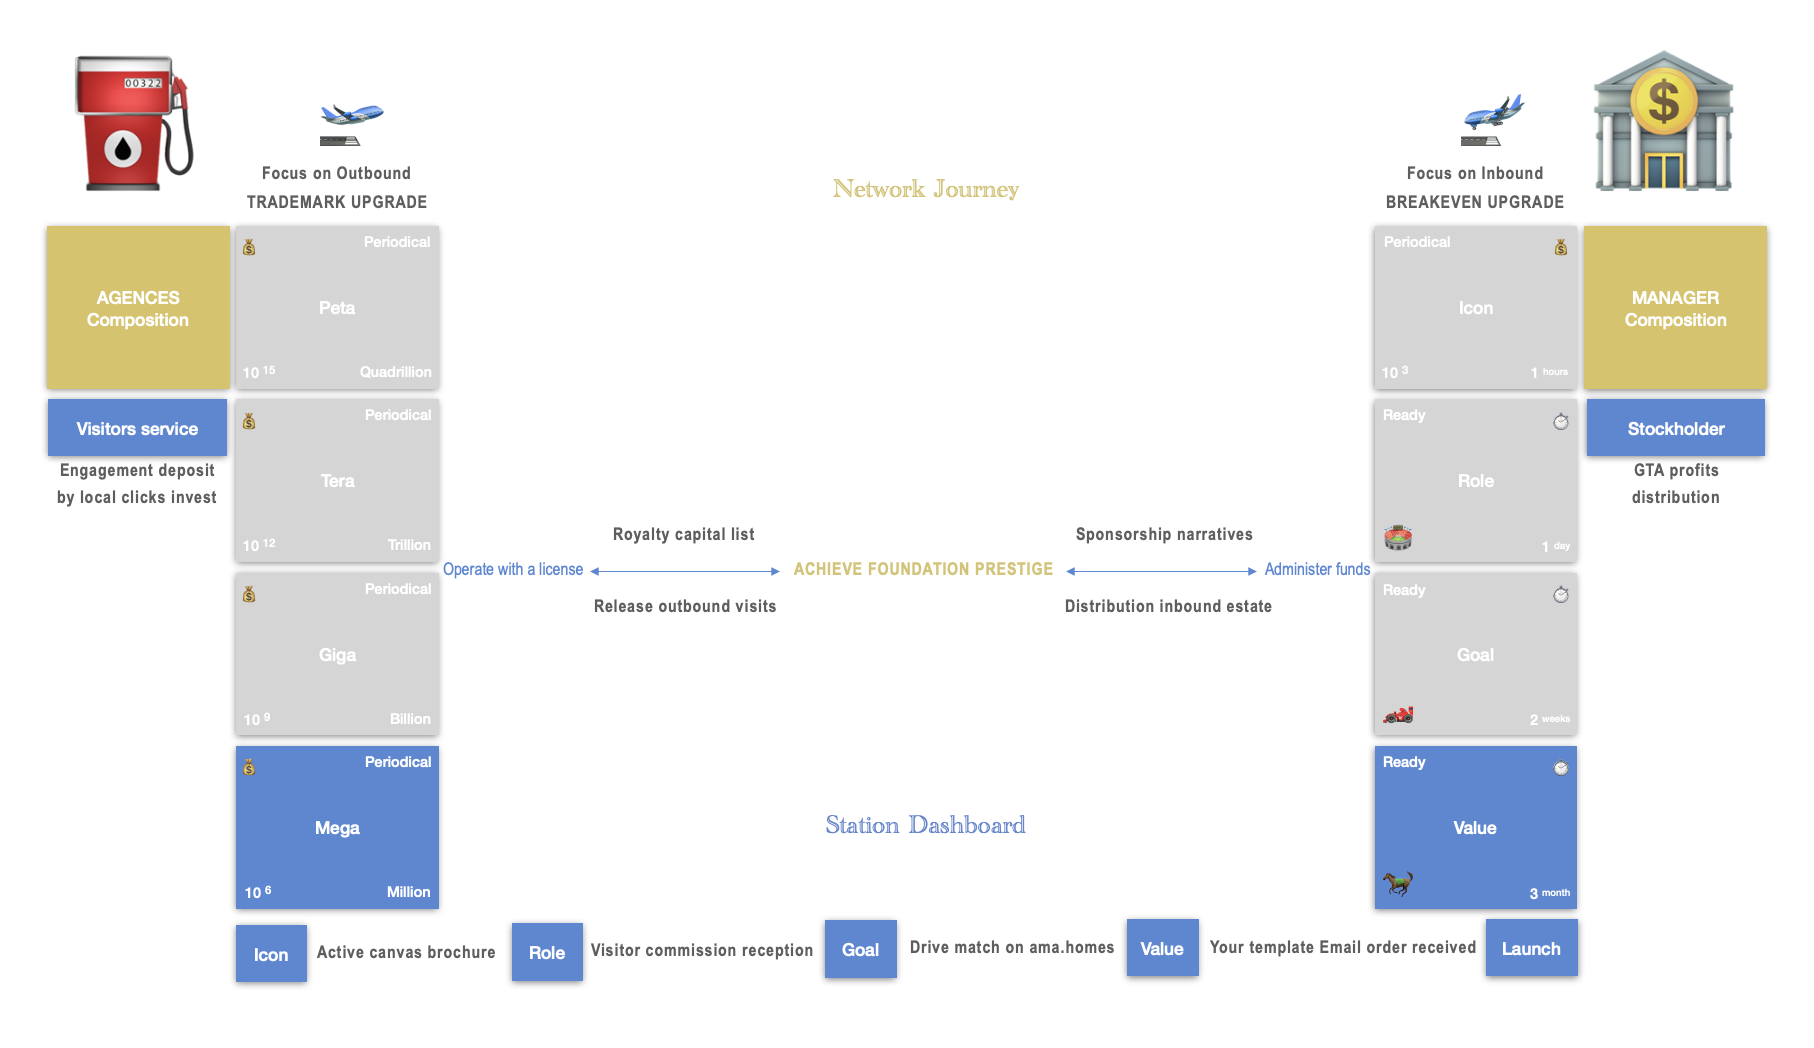
NETWORK CONNECTION
🛫
Outbound protocol
IATA airport code
Active in speculation
Portfolio: [The Unspoken Dialogue.]
This implies a level of personalization so subtle and intuitive that the marketing feels like a natural extension of the customer's desires, rather than a deliberate, intrusive ad.
Experienced Valuation
Passive investment
Back-end Deals (Contract of carriage):[The Social Pulse: Improving Your Experience Based on Your Feedback.]
This uses the word "pulse" to imply that the service is always listening and adapting, communicating a dynamic and responsive improvement process.
Senior Headline city
Day trading
Portfolio candidate lead:[Signifier Roulette: Bet on Your Interpretation.]
This title uses gaming terminology to highlight the arbitrary and unpredictable nature of how meaning is received, framing the contest as a fun gamble on interpretation.
Entry-level Marketing carrier
🛬
Inbound protocol
IATA airport code
Manager, Cash Securities
★ Brochure trader journey map.
Portfolio of Candidate: Domaine name resellers / Installation.
First Name: Marcus
Last Name: Hayes
✓ Tour Receptive Contents Characteristics.
1. Analytical Thinking: Breaking down complex problems into manageable components.
2. Problem-Solving: Developing effective and data-backed solutions.
3. Critical Appraisal: Objectively judging the quality and relevance of data and research.
4. Application: Integrating research findings and data into the decision-making process.
✓ Tour Delivery Contents Features.
Lap Package/Bundle Inclusive: This candidate's career focuses on leading the strategy, development, and launch of e-learning tutorials. They would manage a team to define the content roadmap, ensuring it aligns with audience needs and business goals. This role requires strong leadership skills to influence content direction and drive team performance.
Back-end deals: Her "back-end deals" are performance incentives for reducing file-related technical support tickets.
Our Presentation Topic
Individuals and institutions who own stock are known as "shares sellers" when they offer their shares for sale on the stock market.
Allure station financial store transactions and personal reasons interchange for trade deployment and monitoring: After deploying the validated code, monitor its performance using the rich results reports within Search engines. This tool can detect any invalid items from contest and helps track the performance of your share/portfolio listings. Stock exchanges in wwwave current from round by round ending at the store lap, act as the stock marketplace that brings buyers and sellers together.
Effective staffing inbound call peak time.
This presentation will cover key concepts and strategies related to scheduled inbound call hours and operational efficiency.
Tools for visualizing and optimizing agent schedules.